Posted On:
18 NOV 2026 4:43PM by PIB Delhi
The sustained improvement in financial health across different financial parameters, including, inter alia, capital adequacy, business growth, low slippages, healthy asset quality and outstandingly improved profitability, establishes the complete turnaround in overall functioning of Public Sector Banks (PSBs). It shows that PSBs are not only making profit but also meeting the requirements of credit supply need with improved underwriting capabilities, aided by technology and higher governance standards.
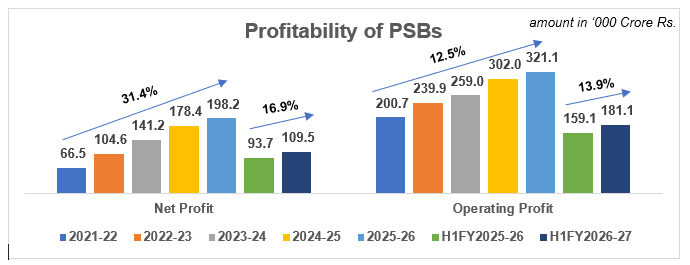
PSBs’ aggregate net profit reached ₹1.10 lakh crore with 16.9% y-o-y growth and aggregate operating profit reached ₹1.81 lakh crore with 13.9% y-o-y growth. Return on assets of PSBs continue to improve, reaching 1.11% with y-o-y improvement of 3bps. The continued improvement in profitability in both net and operating profit for the fifth consecutive year shows fruitful outcome of enablement of deeply engaged reforms drive and establishment of better governance standards by the Government.
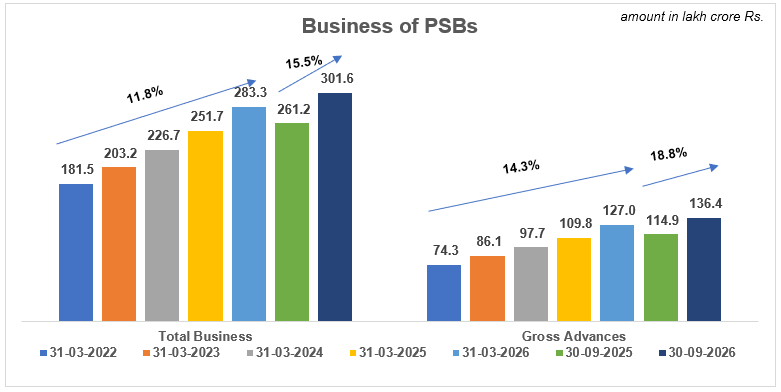
Aggregate business of PSBs grew by 15.5% y-o-y to ₹301.6 lakh crore as on 30.9.2026, crossing the ₹300 lakh crore business mark for the first time. While aggregate deposits grew by 13.1% y-o-y to reach ₹275 lakh crore, the aggregate advances grew at 18.8% y-o-y to reach ₹136.4 lakh crore. The robust credit growth having evenly panned out across different segments, i.e. Retail, Agriculture, MSME, shows PSBs’ continued support to grassroot economic development, inculcation of entrepreneurship and deepening financial inclusion. Credit growth for retail, agriculture and MSME loans was recorded at 17%, 19.5%, 20.4%, respectively.
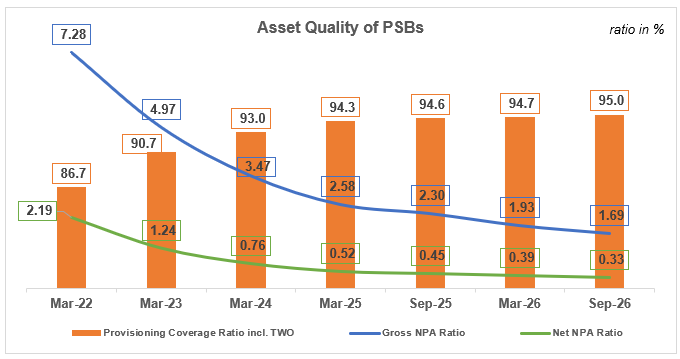
PSBs’ asset quality remains in continual improvement, recording another long-time low, with Gross NPA ratio declining to 1.69% and Net NPA ratio declining to 0.33%. Low levels of NPAs are aided by better underwriting standards visible through low slippages of 0.62% and continually focused collections efforts visible through improved recoveries and upgradations of 21.1%. All PSBs are now having provisioning coverage ratio of above 90%, reflecting prudent banking practices and resilient financial performance.
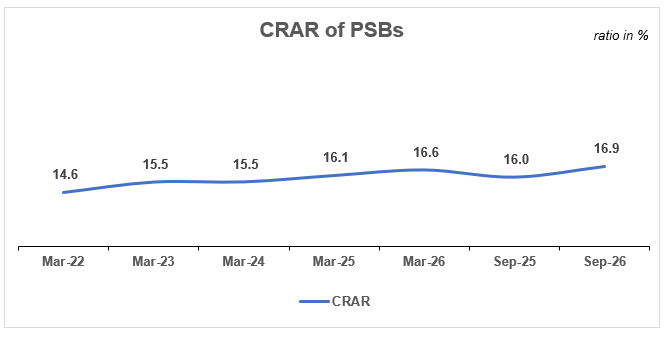
Capital buffers of PSBs remain well above regulatory minimum benchmark through higher retained earnings and strong capital raising, showing availability of adequate cushion to support credit growth while also having capability to absorb systemic shocks. CRAR of PSBs was at 16.89% as on 30.9.2026, improved by 93bps y-o-y. The improvement was also aided by decline in RWA density by 94bps y-o-y to 47.9%.
Cost to income ratio of PSBs also improved by 191 bps y-o-y to 47.38% for H1FY2026-27, aided by decline in cost per asset to 1.60% by 14bps y-o-y. The improved operational efficiency shows gains of investment in technologies and digital transformation, a reflection of efficient cost management.
Performance of PSBs is true reflection of outcomes of institutionalisation of reforms by the Government in PSBs, primarily aimed at better governance standards, improved operational efficiency, prudency in banking practices, enhanced risk management and continual adaptability of technology. The steps taken by the Government in improving operational standards of PSBs is now being reflected in the financial performance, aimed supporting India’s growth aspirations of Viksit Bharat 2047.
***
KT/KMN